Our fix and flip loan programs are designed for real estate investors who need quick closings, rehab funding, and flexible underwriting based on the property’s after-repair value (ARV).
Who Fix and Flip Loans Are Designed For
Fix and flip loans are ideal for real estate investors purchasing non-owner-occupied properties with the intent to renovate and resell for profit. These loans are commonly used by both first-time and experienced investors working on single-family, condo, or 2–4 unit multifamily renovation projects. We also have lenders who will lend on 5+ unit multifamily projects for those with direct experience.
Property investors purchasing distressed or value-add properties
Investors completing cosmetic or full-scale renovations
Borrowers needing fast closings and short-term financing
Investors planning to sell or refinance after renovations
Mid-construction projects where rehab funds have run out and the project has enough equity available to refinance
How Fix and Flip Loans Work
Fix and flip loans are short-term real estate loans that fund the purchase of an investment property and may also include renovation costs. Loan approval is primarily based on the property, renovation scope, and projected after-repair value rather than personal income.
Funds for renovations are typically disbursed in stages as work is completed, allowing investors to manage project cash flow efficiently. Most fix and flip loans are interest-only during the renovation period.
Key Features of Fix and Flip Loans
Financing based on after-repair value (ARV)
Short-term loan options for purchase and refinance
Rehab funding available for qualified projects
Fast approval and closing timelines
Flexible underwriting for real estate investors
No owner-occupancy required
Fix and Flip Purchase and Refinance Options
Fix and flip loans can be used for both property purchases and refinances. Purchase loans help investors acquire and renovate properties, while refinance loans allow investors to access equity after renovations are completed.
Many investors use fix and flip refinances as part of a BRRRR strategy or transition into longer-term rental financing such as a DSCR loan after the rehab phase.
In many instances, we can help borrowers who are mid-construction and need additional funds. This adds a few more layers to qualify but we have excellent resources that help borrowers get their projects back on track.
Fix and Flip Loan Terms at a Glance
Fix and flip loans at a glance
Feature
Typical range
Loan term
6 to 24 months (commonly 6, 12, 18, or 24)
Closing time
Typically 10–15 days, sometimes as little as 5
Purchase leverage
Up to 90% of purchase price for newer borrowers; up to 92.5% loan-to-cost (LTC) with proven experience
Rehab funding
Up to 100% of the rehab budget, released in draws
Maximum loan-to-ARV (LTARV)
Commonly 75%
Example rates
About 11.99% (newer borrower) to 8.99% (5 completed projects), interest-only
Typical minimum mid-FICO
660–680 (some programs have no FICO requirement)
Property types
Single-family, condo, townhome, 2–4 units; 5+ units with direct experience
Examples are indicative of terms that may be offered and are not guaranteed. Actual terms vary by lender and each borrower’s scenario.
Recent Closed Fix and Flip Deals
Here are a few recent fix and flip loans we closed for investors. Borrower names and property addresses are withheld for privacy.
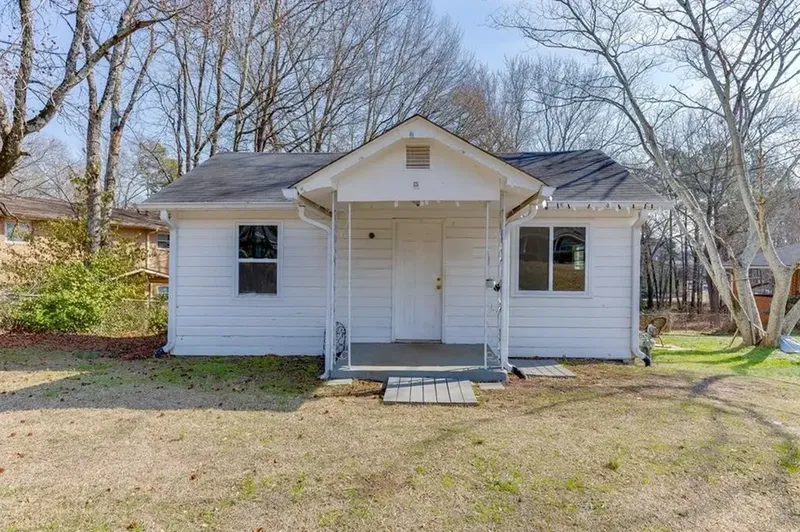
Deal 1
Single-family home · Lawrenceville, GA
Purchase
Before renovation
Purchase price
$175,000
Rehab budget
$57,000
After-repair value (ARV)
$320,000
Loan amount
$208,980
Leverage
90% LTC
Term & rate
12 months at 8.99% fixed
Time to close
Closed in 2 weeks from application
Exit strategy
Sell
Purchase priceRehabRemaining to ARV
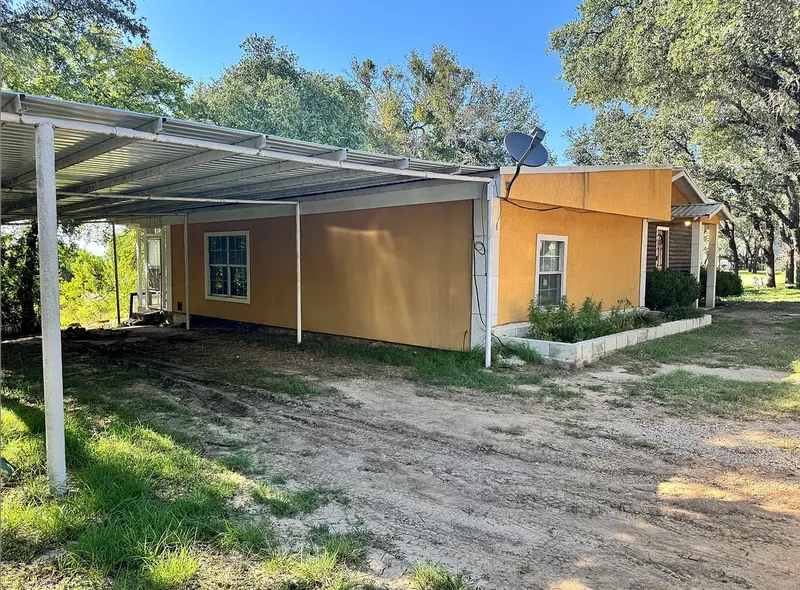
Deal 2
Single-family home · Brownwood, TX (rural)
Cash-out refinance + rehab funding
Before renovation
As-is value
$210,000
Rehab budget
$25,000
After-repair value (ARV)
$280,000
Loan amount
$162,000
Leverage
80% LTC
Term & rate
12 months at 9.50% fixed
Time to close
Closed in 10 days from application
Exit strategy
Sell
As-is valueRehabRemaining to ARV
Deal 3
Single-family home · Port Royal, SC
Purchase
Before renovation
Purchase price
$440,000
Rehab budget
$106,050
After-repair value (ARV)
$590,000
Loan amount
$472,000
Leverage
86% LTC
Term & rate
12 months at 8.99% fixed
Time to close
Closed in 14 days from application
Exit strategy
Sell
Purchase priceRehabRemaining to ARV
Examples of past transactions only. Terms vary by lender, property, and borrower, and past results do not guarantee future terms. Leverage shown as loan-to-cost (LTC).
Fix and Flip Loan FAQs
Is a fix and flip loan the same as a hard money loan?
Fix and flip describes what the loan is for. Hard money describes the type of lender. Most fix and flip loans are funded by private or hard money lenders, so the two overlap. The real differences are in each program: rate, fees, leverage, how rehab funds are released, and term. We compare programs from multiple private lenders to find the best fit for your project.
How fast can a fix and flip loan close?
Many fix and flip loans can close significantly faster than traditional mortgages, depending on the project details, borrower experience, and documentation readiness. Typically, we close fix and flip loans in 10–15 days, and sometimes in as little as 5 days. These timelines are heavily reliant on borrower and third-party response times. In other words, the lenders can only move as quickly as you and your team can.
What credit score is needed for a fix and flip loan?
Credit score requirements vary by program and lender. Approval is often based on the overall strength of the deal rather than credit alone. Generally speaking, most lenders require a mid-FICO of 660–680 or higher to qualify. However, some programs have no FICO requirements at all.
Do I need cash reserves to qualify for a fix and flip loan?
Most of the time, yes. Reserves show that a borrower can close the loan and also begin renovations with cash on hand, so some work can be completed before requesting the first draw for reimbursement. There are exceptions, but the requirement is usually a percentage of the rehab budget plus 3–6 months of interest-only payments, in addition to funds for the down payment and closing costs/fees. This detailed information will be provided on each quote that is issued to you.
Do I need prior fix and flip experience?
Experience requirements vary by loan program. Some lenders require previous projects, while others offer options for newer investors with strong deals. Typically, the more experience a borrower has, the better the loan terms that will be available, such as lower rates and fees.
Full property address of the property you intend to purchase
The purchase price you will offer
Estimated renovation budget and brief overview of the scope of work (light rehab versus moving walls, fixing foundations, adding square footage, etc.)
Expected ARV once renovations are completed
Timeline to complete the renovations
How title is going to be held (individual, entity, or trust)
Borrower’s experience level and exit strategy (sell or refinance to hold as a rental)
Borrower’s estimated FICO scores
Borrower’s current liquidity available
Refinance transactions
Full property address of the property you intend to refinance
The purchase price and date of original acquisition
Amount of rehab spent on improvements since acquisition, if any
Current debt owed on the property
Estimated renovation budget and brief overview of the scope of work (light rehab versus moving walls, fixing foundations, adding square footage, etc.)
Expected ARV once renovations are completed
Timeline to complete the renovations
How title is currently held or will be held at closing (individual, entity, or trust)
Borrower’s experience level and exit strategy (sell or refinance to hold as a rental)
Borrower’s estimated FICO scores
Borrower’s current liquidity available
Mid-renovation transactions: same as a refinance, plus
Estimated as-is value of the property in its current condition
Amount of rehab spent so far
Amount of rehab budget remaining to complete
A detailed narrative explaining why the project is incomplete
Current photos or videos of the project as it currently sits
This information is all we need to provide a soft quote, which often takes as little as a few hours.
Need Additional Info or Have Other Questions?
Please visit our comprehensive FAQ page for more info or complete our Quick App to get your quote started now.
Start Your Fix and Flip Quote
Evaluating a fix and flip opportunity? The first step is completing a short loan intake form. This allows us to review your project and discuss available financing options, including DSCR Loans, Fix and Flip Loans, and New Construction Loans.
This website uses cookies.We use cookies to analyze website traffic and optimize your website experience. You can accept or decline analytics and advertising cookies. See our Privacy Policy.