DSCR Loans, or Debt Service Coverage Ratio loans, are tailored financing solutions for investment properties that allow investors to qualify based on the rental income generated from the property, instead of relying on personal tax returns or employment income. These DSCR loans are specifically designed for investors aiming to purchase or refinance rental properties, offering the flexibility needed for scaling portfolios.
What Is a DSCR Loan?
A DSCR loan (Debt Service Coverage Ratio loan) is a type of investment property loan that evaluates the property’s ability to generate enough rent income to cover mortgage payments and expenses. Instead of relying on personal income, DSCR loans focus on the property’s cash flow — making them ideal for investors who want to grow rental portfolios without traditional income documentation.
How DSCR Loans Work
With a DSCR loan, lenders calculate the ratio by dividing a property’s rental income by the total debt payments (PITIA: principal, interest, taxes, insurance, and association fees). A DSCR of 1.0 or higher generally shows that rental income can cover the mortgage obligation. Most lenders use this method on 1–8 unit residential properties. Buildings with 9 or more units are financed as commercial loans, where DSCR is one qualifying factor rather than the primary method. It is calculated from net operating income (versus gross rents), and the minimum is usually 1.25 or greater.
For example, if a single-family residential property generates $2,000 in monthly rent, and the monthly PITIA payment is $1,800, the DSCR would be 1.11 — which many lenders view as a qualifying cash-flow ratio.
DSCR Loans for Purchase and Refinance
Purchase DSCR Loans: Use DSCR financing to acquire rental properties using the rental income potential of the property, not your paycheck.
Refinance DSCR Loans: Refinance existing investment properties to improve cash flow, lower payments, or pull equity out for future investments.
DSCR Loan Features and Investor Benefits
Qualify based on property cash flow, not personal income
No employment documentation required
No DTI calculation; personal income is not a factor
Works for single-family and multifamily investment properties
Flexible terms (often up to 30 or 40 years) and features such as interest-only periods. Loans can be fully amortized with fixed rates or an adjustable-rate mortgage (ARM).
Used for purchase, refinance, or cash-out strategies on properties that are rent-ready or currently rented out. Properties needing extensive repairs or renovations do not normally qualify.
Who Qualifies for a DSCR Loan?
DSCR loans are best suited for real estate investors with rental properties that produce steady rental income. Typically lenders consider:
Property cash flow sufficient to cover mortgage payments
Adequate reserves to support down payment + closing costs
Property appraisal supporting fair market rent
Credit profile and property type requirements vary by loan program
Seasoning requirements for refinances. Many lenders require 6 months or more on title before qualifying for a cash-out refinance. We work with several BRRRR-friendly lenders who have zero or as little as 3 months of seasoning required.
When Investors Use DSCR Loans
Building a rental portfolio using rental income to qualify
Refinance existing rentals to lower monthly payments or access equity
Acquire multifamily or small apartment buildings
Investors who are self-employed or without traditional income verification
Investors who have reached the conventional lending cap of 10 financed properties
To refinance after completing a fix and flip property. Many investors choose to hold long term as a rental.
DSCR Loan Terms at a Glance
DSCR loans at a glance
Feature
Typical range
Minimum DSCR
1.00 for 1–8 unit properties (gross rents / PITIA); 1.25 or higher for 9+ units (NOI / PITIA)
Loan term
Often up to 30 or 40 years; fixed-rate, interest-only, and ARM options
Leverage
Typically up to 80% loan-to-value (LTV); varies greatly by scenario
Interest rates
Based on current market conditions, credit profile, leverage, DSCR, and property type; quoted for each scenario
Typical minimum mid-FICO
660–680 (lower scores possible with reduced leverage and higher rates)
Cash reserves
Usually 3–6 months of the total mortgage payment, plus down payment and closing costs
Closing time
Generally 25–35 days from submission
Refinance seasoning
Many lenders require 6+ months on title; BRRRR-friendly lenders may require 0–3 months
Property types
Single-family rentals, 2–8 unit multifamily, condos, townhomes, and small portfolios
Documentation
No tax returns or W-2s; qualification is based solely on the property’s income and the borrower’s credit profile
Terms are indicative of what may be offered and are not guaranteed. Actual terms vary by lender, property, and each borrower’s scenario.
Recent Closed DSCR Deals
Here are a few recent DSCR loans we closed for investors. Borrower names and property addresses are withheld for privacy.
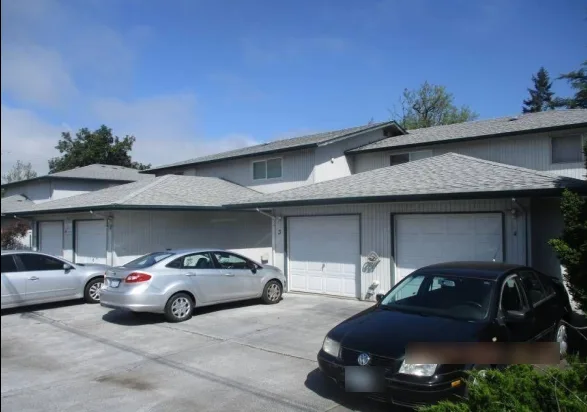
Deal 1
Quadplex · Springfield, OR
Cash-out refinance · Leased
Appraised value
$700,000
DSCR
1.4
Loan amount
$490,000
Term & rate
30-year fixed, fully amortized, 6.75%
Prepayment penalty
3 years
Time to close
Closed in 28 days from application
Loan-to-value (LTV)
70%
Loan amountRemaining equity
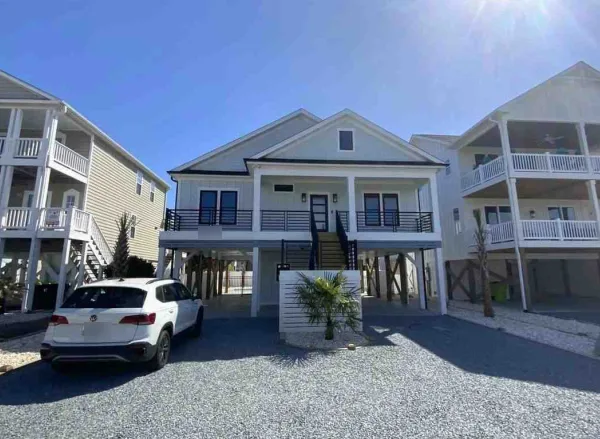
Deal 2
Single-family beach home · Holden Beach, NC
Cash-out refinance · New construction · Short-term rental
Appraised value
$900,000
DSCR
1.3
Loan amount
$480,000
Term & rate
30-year fixed, fully amortized, 5.99%
Prepayment penalty
None
Time to close
Closed in 25 days from application
Loan-to-value (LTV)
53%
Loan amountRemaining equity
Deal 3
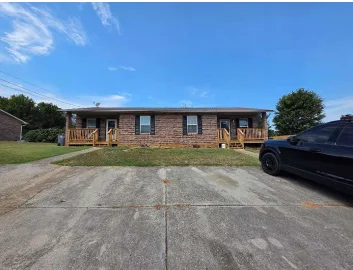
Duplex · Talbott, TN
Cash-out refinance · BRRRR · Fully leased
Purchase price
$100,000
Rehab spent
$65,000
Appraised value
$308,000
DSCR
1.8
Loan amount
$215,600
Term & rate
30-year fixed, fully amortized, 6.75%
Prepayment penalty
3 years
Time to close
Closed in 30 days from application
Loan-to-value (LTV)
70%
Loan amountRemaining equity
Examples of past transactions only. DSCR figures are as calculated by each lender. Terms vary by lender, property, and borrower, and past results do not guarantee future terms.
DSCR Loan FAQs
What is a good DSCR ratio?
A DSCR of 1.0 or higher typically means the property’s rental income covers the mortgage payment. Some programs allow ratios below 1.00, typically with lower leverage or higher pricing, while others may require a higher DSCR depending on loan terms and risk factors.
Typically, 1–8 unit DSCR lenders will use Gross Rents / PITIA to determine the ratio and have a minimum of 1.00. 9+ unit lenders will use NOI / PITIA to determine the ratio and have a minimum of 1.25 or higher.
Do DSCR loans require tax returns or income verification?
No. DSCR loans do not require traditional income documentation such as W-2s or tax returns. Qualification is based solely on the property’s current or potential rental income and the borrower’s credit profile. Personal earnings are not a factor.
What credit score is needed for a DSCR loan?
Credit score requirements vary by lender and loan program, but many DSCR loans are available to borrowers with mid-range credit profiles. Stronger credit may result in better loan terms. Most lenders will require a minimum mid-FICO of 660–680. There are some lenders that will allow lower scores, but leverage and rates worsen considerably.
Do I need cash reserves to qualify for a DSCR loan?
Most of the time, yes. Reserves ensure the borrower can make loan payments if the property becomes vacant or is not leased right away after closing. There are exceptions, but the requirement is usually 3–6 months of the total mortgage payment, in addition to funds for the down payment and closing costs/fees. This detailed information will be provided on each quote that is issued to you.
Can DSCR loans be used for short-term rentals?
Yes. Some lenders allow DSCR loans for short-term rental properties, but qualification methods and income calculations may differ. Eligibility depends on the lender and property type.
The full address of the property you intend to purchase
The purchase price or amount you will offer
Current rents in place, or an estimated amount of rent that will be collected if currently vacant
Current annual property taxes
Current annual insurance
Current HOA fees, if any
How title will be held (as individual, entity, or trust)
Borrower’s estimated FICO scores
Borrower’s experience owning or selling rentals in the past 36 months
Borrower’s current liquidity
Refinance transactions
The full address of the property you intend to refinance
The purchase price you paid and date of original acquisition
Amount of rehab spent on improvements since acquisition, if any
Current debt owed on the property
Current rents in place, or an estimated amount of rent that will be collected if currently vacant
Current annual property taxes
Current annual insurance
Current HOA fees, if any
How title is currently held (as individual, entity, or trust)
Borrower’s estimated FICO scores
Borrower’s experience owning or selling rentals in the past 36 months
Borrower’s current liquidity
Need Additional Info or Have Other Questions?
Please visit our comprehensive FAQ page for more info or complete our Quick App to get your quote started now.
Get Started with Your DSCR Loan Quote
Evaluating a DSCR rental opportunity? The first step is completing a short loan intake form. This allows us to review your project and discuss available financing options, including DSCR Loans, Fix and Flip Loans, and New Construction Loans.
This website uses cookies.We use cookies to analyze website traffic and optimize your website experience. You can accept or decline analytics and advertising cookies. See our Privacy Policy.