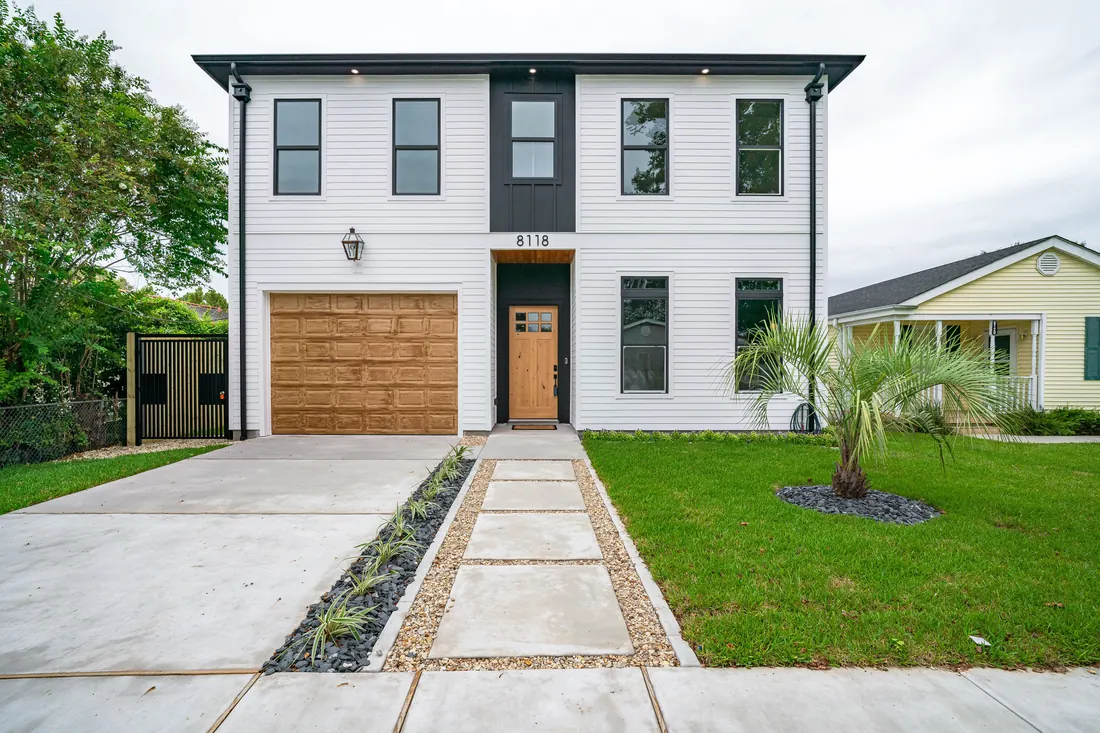
The Crossroads Every Fix & Flip Investor Must Navigate
After the final paint stroke dries and the last appliance is installed, a critical question emerges: should you sell the property for immediate profit or refinance it to add a rental asset to your growing real estate portfolio? This decision isn’t just financial—it shapes your long-term strategy, cash flow trajectory, and scalability. In dynamic markets like Orlando and Tampa, where property values and rental demand continue to rise, the choice carries even greater weight. Thousands of investors complete rehab projects each year, but only a fraction leverage them to build lasting wealth through strategic hold decisions.
In this guide, you’ll learn how to evaluate your post-renovation options with clarity and confidence. We’ll break down the financial implications of selling versus refinancing, spotlight key metrics like cash-on-cash return and DSCR (Debt Service Coverage Ratio), and help you align your decision with your broader investment goals. You’ll also discover how refinancing into an investment-grade loan—such as a DSCR loan—can preserve equity while unlocking cash for future deals. Whether you're focused on rapid turnover or building passive income streams, understanding this pivotal fix-and-flip crossroads is essential for long-term success.
The Sell Strategy: Capitalizing on Immediate Gains and Market Momentum
Choosing to sell your flipped property is a powerful move that prioritizes speed, liquidity, and strategic reinvestment. This approach allows investors to lock in profits quickly, especially in fast-moving markets like Orlando and Tampa, where rising values and strong buyer demand can maximize returns. When you sell, you convert your after-repair value (ARV) into tangible cash—often within 30 days of listing—freeing up capital to fund your next acquisition without relying on loan seasoning periods or rental stabilization.
Key benefits of the sell strategy include:
- Instant profit realization: Access 100% of your equity (minus closing costs) to use as down payments on future flips
- Faster deal cycle turnover: Reduce idle time between projects and compound returns through volume
- Optimal market timing: Exit during peak appreciation phases, avoiding potential downturns or rising inventory levels
To get the most from your sale, monitor local indicators like days-on-market, price per square foot trends, and open house feedback. These signals help pinpoint the ideal window to list. Additionally, reduce holding costs—such as taxes, insurance, and interest—by minimizing vacancy time post-renovation.
Selling is particularly effective if your goal is rapid portfolio growth through repeated flips. By consistently capturing gains and redeploying capital, investors can scale quickly while maintaining financial flexibility in changing market conditions.
Unlock Long-Term Wealth: How Refinancing Powers Your Investment Strategy
When a fix-and-flip project reaches completion, savvy investors don’t just pocket profits—they leverage them. Refinancing transforms short-term gains into long-term wealth by replacing high-cost hard money or private loans with stable, long-term financing. This strategic move locks in lower interest rates, extends repayment terms, and immediately improves cash flow the moment the new loan closes.
By refinancing into a conventional or portfolio investment loan, investors shift from a speculative stance to one of ownership and growth. This process builds equity faster by reducing monthly debt obligations, allowing more rental income to flow directly into your pocket or be reinvested into other deals. Over time, consistent refinancing across multiple properties creates reliable passive income streams—especially in high-demand markets like Orlando, Tampa, or similar growth zones where property values and rents continue to rise.
To maximize this approach:
- Wait until the property is fully leased and stabilized to qualify for the best terms
- Use strong rental income history to strengthen your application
- Target lenders who specialize in investment properties and understand cash flow underwriting
Refinancing isn’t just about saving money—it’s about resetting the financial foundation of your asset. Done right, it turns a one-time profit into lasting equity and income, fueling the next phase of portfolio growth without additional risk.
Crunching the Numbers: Selling vs. Refinancing Your Flip
When your rehab project is complete and the market is hot, the big question becomes: cash out or hold on? Understanding the financial ripple effects of selling versus refinancing is critical for maximizing returns in real estate investing. Both paths have distinct impacts on cash flow, tax obligations, and overall return on investment—your strategy should align with your long-term portfolio goals.
Selling delivers immediate gross profit, especially strong in high-appreciation markets like Orlando or Tampa. You realize 100% of your equity upfront, which can be redeployed into your next deal. However, short-term capital gains taxes apply if held under one year, reducing net proceeds. While cash flow ends with the sale, the lump sum can fuel multiple new acquisitions or down payments.
Refinancing allows you to pull out equity tax-free through a non-recourse cash-out refinance, typically after a seasoning period of 6 months or more (as little as 0–3 months with some BRRRR-friendly lenders). This preserves ownership, enabling long-term appreciation and ongoing rental income. Your cash flow shifts from a one-time win to monthly positive income—ideal for building a sustainable portfolio. While future cap gains may apply upon eventual sale, the initial tax hit is avoided.
Key considerations:
- Use after-repair value (ARV) to maximize refinance loan amounts
- Compare net proceeds post-commission and closing costs when selling
- Factor in holding costs, tax brackets, and reinvestment timelines
Choose based on whether you prioritize liquidity or long-term wealth building.
6 Key Factors That Determine Your Fix & Flip Exit Strategy
When the rehab's complete and the listing photos are live, real estate investors face a critical crossroads: sell for a lump-sum profit or refinance into long-term rental income. The right choice hinges on more than gut instinct—it requires a strategic evaluation of market dynamics, financial metrics, and investment goals.
- Current Market Conditions
In seller’s markets with rapid appreciation—like Orlando or Tampa—flipping capitalizes on peak demand. However, if inventory is rising or days-on-market are extending, holding and refinancing may be safer. Monitor local absorption rates and buyer sentiment to time your move. - Property Location & Rental Demand
High-growth ZIP codes with strong job markets and population inflows often make ideal hold candidates. If your property sits near universities, hospitals, or tech hubs, long-term cash flow could outperform a one-time flip profit. Analyze neighborhood rent comps and tenant profiles to forecast stability. - Interest Rate Environment
Low-rate climates favor cash-out refinancing, locking in affordable financing for portfolio expansion. When rates climb, flipping frees capital unencumbered by high debt service—critical for preserving ROI. Always stress-test your numbers at higher rate scenarios. - Investor Goals: Cash Flow vs. Liquidity
Are you stacking rental units or reinvesting profits into your next flip? Short-term sellers gain liquidity for new deals; long-term holders build equity and passive income. Define whether your focus is velocity or value accumulation. - After-Repair Value (ARV) vs. Rental Yield
Run the numbers: does the ARV justify passing up above-market rental yields in a high-demand area? A property with a $400,000 ARV may appraise lower for refinance, but strong rental income can offset that gap over time. - Financing Flexibility
DSCR loans enable seamless transitions from flip to rental, qualifying based on projected income—not personal tax returns. This makes refinancing faster and more accessible than traditional residential loans.
Should I Hold or Sell After a Renovation? Your Fix & Flip FAQs Answered
What are the main factors in deciding whether to hold or sell after a renovation?
The decision depends on your investment strategy, market dynamics, and financial objectives. Selling provides immediate liquidity—ideal for reinvesting in additional flips—while holding builds long-term wealth through rental income and equity appreciation. Evaluate the property’s location, cash flow potential, and local market trends to determine which path aligns best with your goals.
What financing options exist for investors who want to hold?
Once renovations are complete, investors can refinance into an investment property loan such as a DSCR (Debt Service Coverage Ratio) loan, which qualifies based on the property’s rental income rather than personal tax returns. Other viable options include portfolio loans or private financing, all of which support long-term ownership and scalable portfolio growth, particularly in high-demand areas like Orlando and Tampa.
How do I assess the risks of holding versus selling?
Selling eliminates ongoing risks like tenant turnover, maintenance costs, and market downturns, offering a clean exit with a defined profit. Holding introduces management responsibilities but can yield stronger long-term returns if rental demand remains steady. Always run worst-case scenario analyses, accounting for vacancy rates and unexpected repairs.
Is it better to reinvest profits into another flip or keep the property as a rental?
Consider your capacity and goals. Reinvesting accelerates deal velocity; holding builds passive income. Many investors use a hybrid model: complete several flips, then refinance one property to create a stable income stream.
Can I refinance immediately after completing a flip?
Many lenders require a seasoning period of 6 months or more (some BRRRR-friendly lenders require as little as 0–3 months) post-purchase or post-renovation before approving a cash-out refinance. DSCR loans are often the most accessible route after a flip due to their income-based underwriting.
How does location influence my decision to hold or sell?
Markets with strong population growth, job expansion, and high rental demand—like many Florida cities—favor holding. In slower or overheated markets, selling may offer a safer, more profitable exit.
Should I hold my flipped property in an LLC?
Yes. Using an LLC provides liability protection, separates personal and business assets, and simplifies future refinancing or resale.
Your Strategic Path Forward: Aligning Action with Vision
The decision to sell or refinance your fix-and-flip property isn't just a financial choice—it's a strategic pivot point that defines your investor trajectory. By now, you’ve evaluated key metrics like after-repair value (ARV), cash-on-cash return, debt service coverage ratio (DSCR), and local market dynamics in high-growth areas such as Orlando and Tampa. You understand that selling offers immediate liquidity, ideal for reinvesting into new deals and maximizing deal velocity. Conversely, refinancing allows you to retain a cash-flowing asset, build long-term equity, and benefit from ongoing appreciation—all without triggering short-term capital gains taxes.
To make your final decision, revisit your core investment goals: Are you prioritizing rapid portfolio growth or sustainable passive income? If reinvestment speed is key, selling and redeploying profits may be the optimal route. If wealth preservation and monthly cash flow are your focus, refinancing into an investment-grade loan—like a DSCR loan—can secure favorable terms based on rental income rather than personal tax returns.
Your next steps should include:
- Running a side-by-side comparison of net proceeds from a sale versus projected rental cash flow
- Confirming seasoning requirements for refinancing with your lender
- Assessing property management capacity if holding long-term
Ultimately, every flip presents an opportunity to advance your larger strategy. Whether you sell or refinance, make sure your move reflects a clear, intentional path toward your long-term real estate success. When you're ready to act, consult a lender who specializes in investment property financing to streamline your next phase with confidence.
Submit one short intake form and we will review financing options for your property, project, and strategy.